
Stress-Test and Submit a Clear Scenario
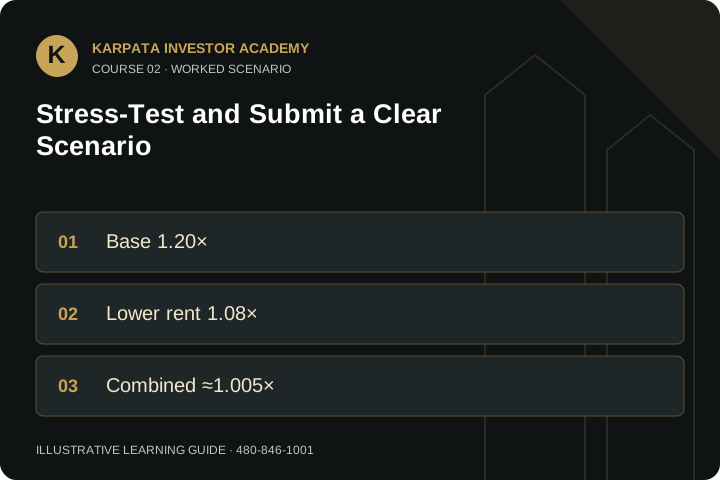
Coverage is a snapshot of assumptions. A useful financing decision asks what happens when those assumptions weaken. Test lower rent, a larger insurance bill, reassessed taxes, unexpected vacancy and the proposed loan’s eventual payment structure. Separate a temporary liquidity shock from a recurring operating deficit: reserves can bridge a vacancy, but they do not repair permanently negative economics.
Change one variable first to understand its effect, then combine reasonable downside assumptions. If coverage is already borderline, a small cost increase may move the property below the selected target. Increasing the down payment may reduce principal and interest, but it also consumes cash that could protect the investment. Evaluate both coverage and post-closing liquidity. Do not inflate rent projections or omit known costs to make a ratio pass.
A lender-ready scenario identifies property address and units, purchase or refinance purpose, supported rent, requested loan amount, value basis, expected PITIA, credit profile, available reserves and rental strategy. Include the documents supporting key inputs and explain any gaps. Ask which assumptions remain preliminary, what happens if the appraisal changes, and whether a prepayment charge or future reset affects the exit. Complete the knowledge review after you can explain the ratio and the investment economics in your own words.
Worked example
Base rent $2,400 and PITIA $2,000 yield 1.20. A 10% rent reduction gives $2,160 and 1.08. Adding $150 monthly insurance cost gives $2,150 PITIA and 2,160 ÷ 2,150 ≈ 1.005. Coverage is almost at 1.00 before management, repairs or replacement savings.
Mini glossary
- Sensitivity analysis
- Testing how changed assumptions affect results.
- Liquidity
- Cash or readily available funds for obligations.
- Exit strategy
- A documented plan to repay or refinance financing.
Put it into practice
Run base, lower-rent and combined-downside cases. Write a one-page scenario with sources for every input and a realistic reserve plan. Identify one condition that would cause you to decline the investment. Then use the cheat sheet and take the review without relying on optimistic estimates.
Recommended reading
Use these primary sources for context. Individual lender requirements can change; confirm the current program for your transaction.