
Build the Full PITIA Payment
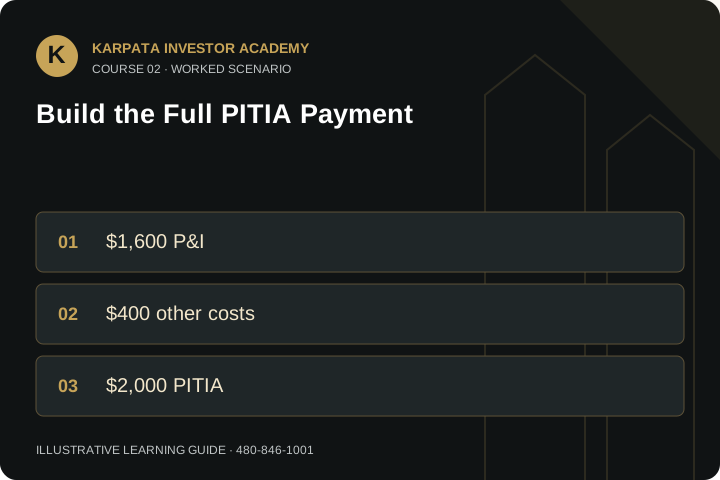
The denominator deserves as much attention as rent. Principal repays borrowed money; interest pays for use of that money. Property taxes, insurance and association dues are continuing property obligations. Even when taxes or insurance are not escrowed, they may belong in the qualifying payment. Dividing rent only by principal and interest can make a weak deal appear strong.
Use the proposed loan amount, rate, amortization and payment structure. An interest-only payment can differ materially from an amortizing payment. The program may qualify at the actual interest-only payment or another required payment, so confirm the rule. A teaser rate, future reset or balloon maturity also matters to the investor’s risk even if the initial ratio qualifies.
Convert annual taxes and insurance into monthly amounts and verify the documents behind them. A seller’s old tax bill may not represent the post-acquisition assessment. An insurance quote should match rental use, location and required coverage. Ask about association dues, special assessments and mortgage insurance where applicable. Avoid counting taxes and insurance twice if the quoted payment already includes them. Keep a dated input sheet so revised terms produce a traceable revised ratio rather than a silent change.
Worked example
Proposed principal and interest are $1,600 monthly, annual taxes $3,000, annual insurance $1,200 and association dues $50 monthly. PITIA is 1,600 + 250 + 100 + 50 = $2,000. With $2,400 accepted rent, DSCR is 1.20; using only $1,600 would incorrectly show 1.50.
Mini glossary
- Amortization
- Scheduled repayment of principal over time.
- Escrow
- Funds collected for bills such as taxes and insurance.
- Interest-only
- Payments excluding scheduled principal during a defined period.
Put it into practice
Build a five-line monthly payment worksheet. Attach the tax estimate, insurance quote and association statement. Label whether the lender quote includes escrow. Then compare interest-only and amortizing payments and note when any interest-only period ends. Ask which payment is used for underwriting.
Recommended reading
Use these primary sources for context. Individual lender requirements can change; confirm the current program for your transaction.