
Deploy Proceeds and Protect the Portfolio
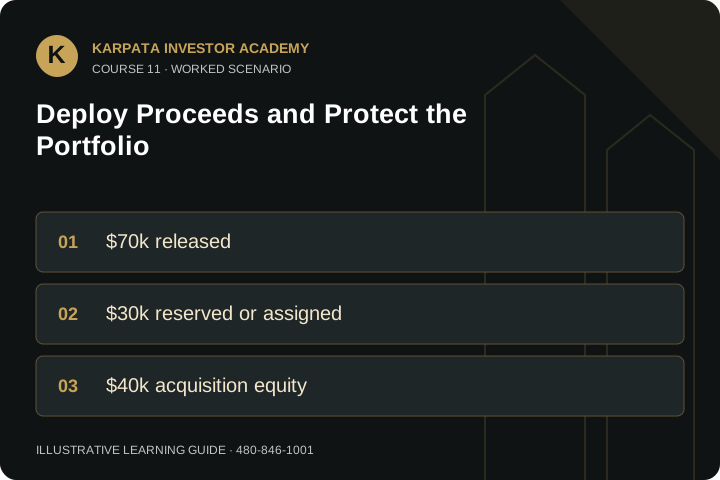
Released capital needs a written allocation plan. Assign money to reserves, planned repairs, transaction costs and the next investment before assuming all proceeds can become a down payment. If another project requires renovation funding or delayed reimbursements, it needs working capital in addition to acquisition equity.
Consider the refinancing property’s maturity, rate structure, prepayment terms and future exit. Equity extraction can reduce flexibility if a later sale triggers charges or if a lower value makes refinancing harder. Borrowing from one property to support another links their risks through the investor’s overall liquidity. Diversification of addresses does not necessarily diversify market, tenant or construction exposure.
Keep a cash schedule for all committed investments. Stress-test simultaneous vacancies, a larger repair and a delay in the new project. Avoid treating the same reserve as protection for multiple obligations at once. Confirm whether loan documents restrict use of proceeds and disclose the intended business purpose accurately. Review actual results after closing and keep enough available cash for contractual debt service. A disciplined cash-out strategy converts part of equity into usable capital while preserving resilience; the right amount may be smaller than the maximum a lender offers. More proceeds are helpful only when the added obligations fit the operating plan.
Worked example
Net cash-out is $70,000. Assign $15,000 to portfolio reserves, $10,000 to known repairs and $5,000 to new-deal costs, leaving $40,000 for acquisition equity. If the next project also needs $12,000 before its first draw, the allocation has a gap unless the acquisition or other funding changes.
Mini glossary
- Use of proceeds
- Planned allocation of borrowed funds.
- Portfolio reserve
- Available funds supporting defined investment obligations.
- Working capital
- Cash covering project expenses before reimbursements or income.
Put it into practice
Allocate every dollar of a hypothetical cash-out distribution. Include reserves and the next project’s first draw gap. Read use-of-proceeds and prepayment conditions. Stress-test two properties together, then decide whether to borrow less, postpone the new acquisition or secure another documented capital source.
Recommended reading
Use these primary sources for context. Individual lender requirements can change; confirm the current program for your transaction.