
Compare Costs, Payments and Cash Flow
A refinance changes both the balance sheet and the operating budget. Calculate the old and proposed payment using the correct loan amount, rate, amortization and escrow assumptions. A larger loan can increase debt service even when the new rate is lower. Separate principal and interest from taxes and insurance so the comparison uses consistent components.
List all transaction costs, including origination, third-party reports, title, legal charges, recording and any prepayment obligation. Costs financed into the new loan still increase debt; they are not free. A simple cost-versus-monthly-savings payback can be useful for a comparable rate-and-term refinance, but a cash-out transaction also delivers capital and changes leverage, making that shortcut incomplete.
Recalculate lender coverage and investor cash flow after the new payment. Include vacancy, management, repairs and replacement savings on the investor sheet without double-counting taxes or insurance. Test higher expenses or lower rent. Compare the expected use of released funds with the cost and risk of the new borrowing, recognizing that future investment returns are uncertain while debt obligations remain contractual. An attractive capital opportunity should not automatically justify weakening the rental’s cash flow or removing its reserve cushion. Evaluate the entire portfolio, not just the immediate deposit.
Worked example
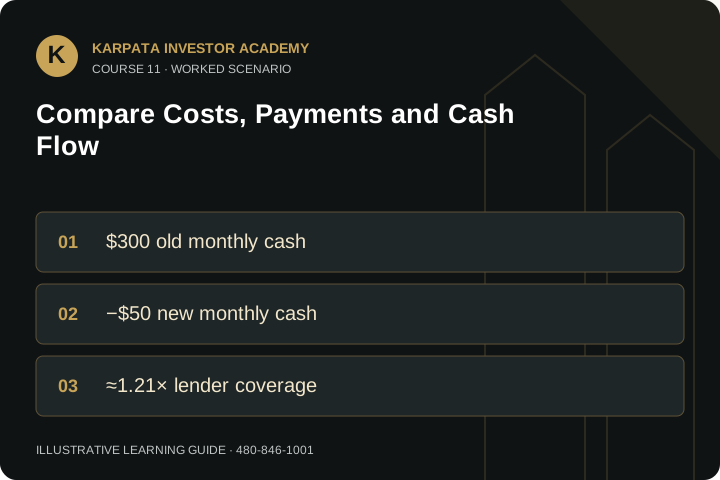
Rent is $2,600. Old PITIA $1,800 and other monthly allowances $500 leave $300 cash. New PITIA $2,150 leaves −$50 with unchanged allowances. Residential DSCR is still about 1.21, but the refinance creates a planned operating deficit. Extra capital must be weighed against that recurring cost.
Mini glossary
- Rate-and-term refinance
- Replacement financing mainly changing debt terms.
- Payback period
- Time for stated savings to offset stated costs.
- Leverage
- Use of debt relative to a defined asset or capital basis.
Put it into practice
Compare old and new lender coverage and investor cash flow. List financed costs separately from cash-paid costs. Test a rent reduction and insurance increase. Write how released capital will be used, what return is uncertain and what new debt payment must be supported even if that investment disappoints.
Recommended reading
Use these primary sources for context. Individual lender requirements can change; confirm the current program for your transaction.