
Leverage, Coverage and Liquidity Tests
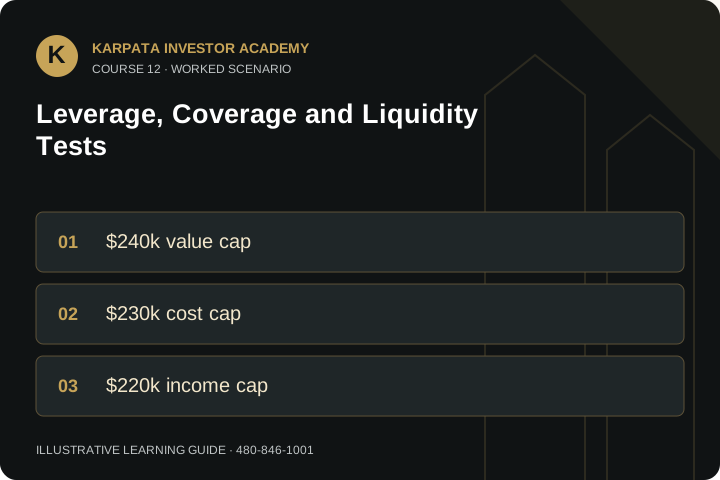
Loan sizing converts the lender’s risk rules into a maximum financing amount. Value leverage, eligible cost, prospective completed value and income coverage may all constrain proceeds. Credit profile, property type, experience, loan size and reserves can impose additional limits or pricing changes. A requested amount is a proposal until those tests are applied.
Use documented inputs and label every assumption. For residential rentals, confirm accepted rent and PITIA. For commercial property, confirm underwritten income and the qualifying debt-service basis. For construction, identify eligible costs and the accepted completed scope. Different products can use different formulas, so compare their definitions before comparing percentages.
After identifying the lowest applicable cap, reconcile gross commitment to net funding and investor cash. Deduct payoffs, fees, reserves and holdbacks as relevant, and map later disbursements. Strong appraised value does not eliminate a coverage shortfall or a draw liquidity gap. Explain how the borrower funds equity and overruns. A transparent sizing table helps the lender evaluate alternatives, such as a smaller loan or different structure, without relying on unsupported rent or valuation changes. The investor should understand which constraint binds and which changes could realistically improve the scenario without weakening the economics elsewhere.
Worked example
Requested loan is $250,000. Value leverage permits $240,000, eligible-cost leverage $230,000 and income coverage $220,000. The preliminary limit is $220,000 before additional underwriting. If the project needs $280,000 total sources, the investor must show $60,000 equity or another permitted committed source.
Mini glossary
- Underwriting
- Evaluation of facts and risk against lending requirements.
- Binding limit
- Constraint producing the smallest permitted loan.
- Net funding
- Usable proceeds after applicable deductions and restrictions.
Put it into practice
Build a sizing table using realistic value, cost and income. Circle the controlling cap and reconcile it with total uses. Ask which input changes require updated approval. Show cash to close and later draw liquidity separately, then explain a permitted funding source for the remaining gap.
Recommended reading
Use these primary sources for context. Individual lender requirements can change; confirm the current program for your transaction.