
Completion and Take-Out Strategy
Completion is both a physical milestone and a financing milestone. Final inspections, occupancy approvals, lien documentation and unfinished punch-list items can affect the last draw, the sale and permanent financing. Schedule these steps explicitly; a building that looks finished may still be unable to produce the documentation required for repayment or occupancy.
For build-for-sale projects, compare supportable net sale proceeds with projected payoff, selling costs and remaining obligations. For build-for-rent projects, underwrite permanent financing using realistic rent, expenses, coverage, valuation and program requirements. A construction lender’s approval does not guarantee a permanent lender’s approval. Identify whether stabilization, lease-up or ownership seasoning must occur before take-out.
Allow time between projected completion and loan maturity for administrative review, marketing, buyer financing or refinance underwriting. Read extension options and costs, and establish a trigger for using contingency or revising the exit. A future appraised value may change with interest rates, comparable sales or rent assumptions. Build a lower-value case before relying on equity extraction. For multiple units or phases, confirm release prices and whether a sale of one unit reduces the remaining commitment. The capital plan is complete only when the last loan dollar has a credible repayment source and the investor can fund any gap.
Worked example
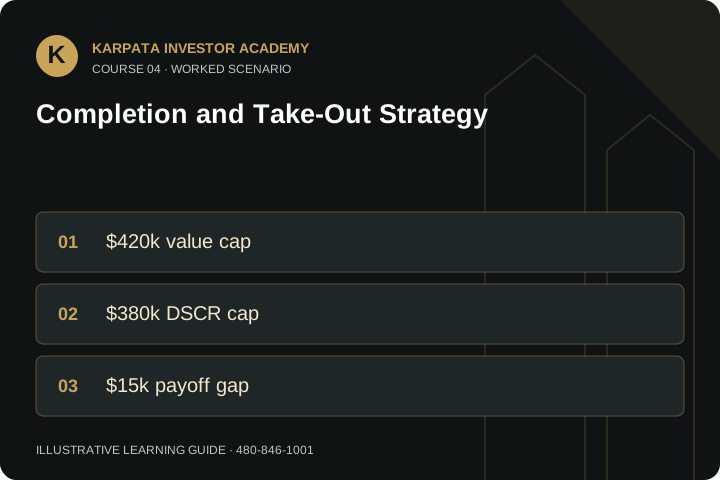
Projected permanent value is $600,000. At an illustrative 70% LTV, the value cap is $420,000. If DSCR limits proceeds to $380,000 and construction payoff is $395,000, the investor needs at least $15,000 plus closing costs. A high finished value does not eliminate the cash gap.
Mini glossary
- Take-out
- Financing replacing an interim construction loan.
- Stabilization
- Reaching sustainable occupancy and operating performance.
- Certificate of occupancy
- Local authorization for permitted occupancy where required.
Put it into practice
List every completion document and its responsible party. Obtain preliminary take-out guidance using conservative income. Test a lower valuation and delayed lease-up. Build a repayment calendar ending before loan maturity, and identify cash sources for a refinance shortfall rather than assuming an automatic extension.
Recommended reading
Use these primary sources for context. Individual lender requirements can change; confirm the current program for your transaction.