
Repeat Only After Testing the Portfolio
Repeat is a portfolio decision, not an instruction to buy the next property immediately. Confirm that the completed rental is performing, the permanent loan has closed and reserves remain adequate. The first project’s paperwork may look successful while its actual maintenance, collections or management costs differ from projections.
Evaluate cash-on-cash return using annual pre-tax cash flow divided by the cash equity denominator you explicitly choose. State whether you are using original equity or capital remaining after refinance; those measures can tell different stories. A very small or zero remaining-capital denominator can produce a dramatic or undefined percentage without making the investment risk-free. Consider total leverage, cash flow and capital commitments as well.
Stress-test the combined portfolio before repeating. Several properties may face vacancy, insurance increases or major repairs at the same time. Keep reserves available rather than automatically using all refinance cash for the next down payment. Record what went differently from the original plan and revise the next acquisition assumptions. Repeat only when the operating results, financing eligibility, management capacity and liquidity support another project. A slower, well-funded cycle can be more durable than a fast cycle depending on rising values and flawless refinance timing.
Worked example
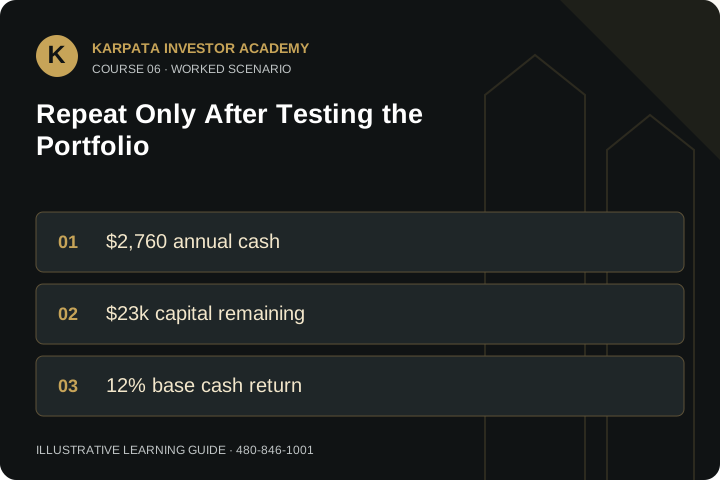
A rental produces $2,760 annual pre-tax cash flow and has $23,000 capital remaining. On that defined denominator, cash-on-cash return is 2,760 ÷ 23,000 = 12%. A $4,000 repair reduces first-year cash flow below zero. The favorable base percentage does not replace a repair reserve.
Mini glossary
- Cash-on-cash return
- Annual cash flow divided by stated cash equity.
- Portfolio liquidity
- Available cash across investment commitments.
- Concentration risk
- Exposure to similar assets, markets or operating pressures.
Put it into practice
Create a post-project review showing actual costs, timeline, rent and cash flow. Calculate return with a labeled denominator and test one major repair. Decide how much refinance cash stays reserved before buying again. Identify management tasks that must be covered when adding another property.
Recommended reading
Use these primary sources for context. Individual lender requirements can change; confirm the current program for your transaction.