
Interest-Only Does Not Mean Low Cost
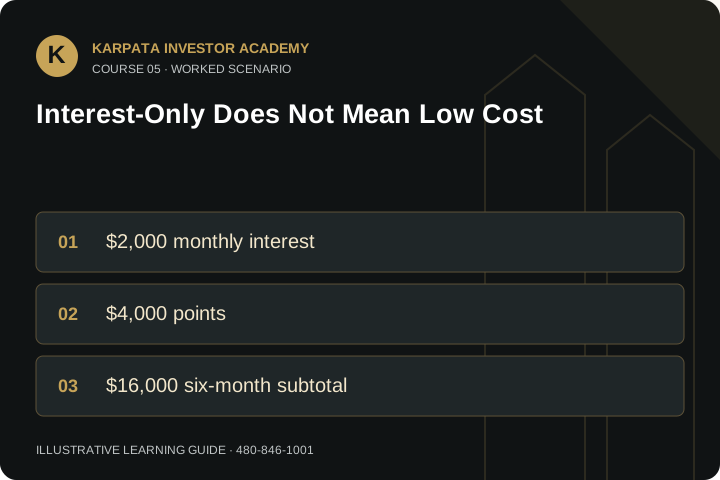
Many bridge loans use interest-only payments. The payment covers interest without reducing principal, so the balance remains due at maturity unless other principal payments are required. A lower monthly payment can help liquidity, but it does not make the loan inexpensive or remove the balloon obligation. Read the note rather than relying on the payment label.
Compute costs across the expected holding period. Include origination points, lender fees, third-party reports, legal charges, inspections, extension charges and any minimum interest or exit fee. One point equals one percent of the applicable loan amount. Verify whether fees are charged on commitment or funded balance, and whether interest accrues on drawn funds or another contractual basis.
Compare offers using the same amount and timeline. A lower rate with larger fixed fees can cost more during a short hold. Conversely, an apparently cheap short-term loan can become costly when delays require extensions. Separate loan cost from property carry, including taxes, insurance, utilities and maintenance. Also distinguish gross loan proceeds from net cash at closing after withheld fees, payoffs or reserves. A financing plan must show what reaches the borrower and what remains owed, not just the headline rate printed on the term sheet.
Worked example
A $200,000 interest-only balance at an illustrative 12% annual rate costs $2,000 monthly. Six months cost $12,000 interest. Two origination points add $4,000, bringing these two costs to $16,000 before other fees and property carry. Principal repayment is still $200,000.
Mini glossary
- Point
- One percent of the defined loan amount.
- Interest-only
- Payment that excludes scheduled principal.
- Balloon
- Remaining principal due at a specified maturity.
Put it into practice
Price two hypothetical offers for six and nine months using identical balances. Include points, fixed fees and extensions. Highlight any minimum-interest clause that could affect an early payoff. Ask for net closing proceeds and a sample payoff calculation before treating the monthly payment as total cost.
Recommended reading
Use these primary sources for context. Individual lender requirements can change; confirm the current program for your transaction.